Social Security Solvency Projected Until 2033: New Report Details
The Social Security Administration projects its trust funds will remain solvent until 2033, according to the latest actuarial report. This report details critical financial outlooks and factors impacting the program's long-term sustainability.
Por: Marcelle em 23 de setembro de 2026
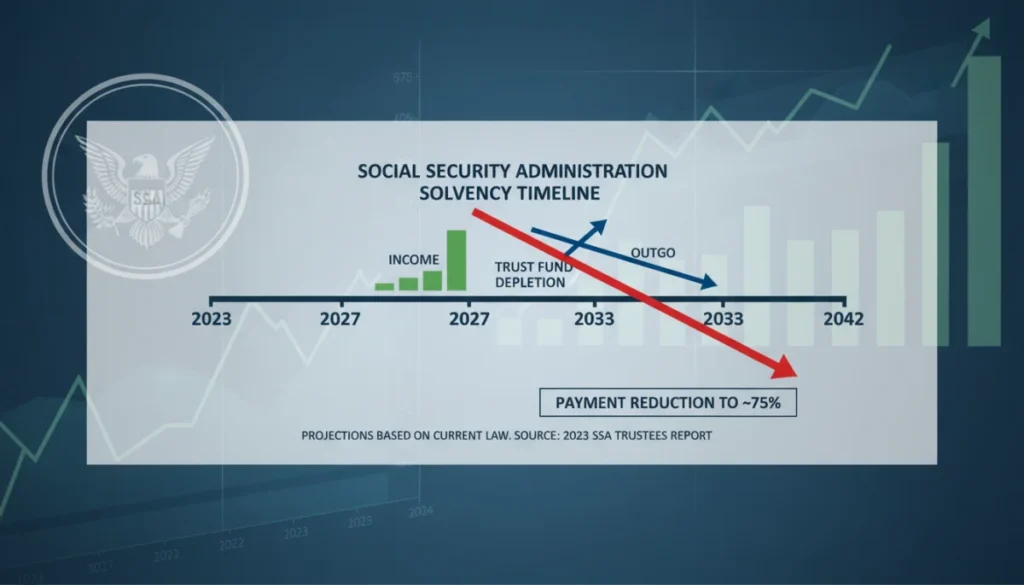
The Social Security Administration’s latest actuarial report projects that its combined trust funds will be able to pay 100 percent of scheduled benefits until 2033, a critical update for millions of Americans relying on these vital programs.
The latest actuarial report from the Social Security Administration brings crucial insights into the financial health of one of America’s most vital safety nets. The report, which outlines the projected solvency of the program’s trust funds, indicates that the system is expected to meet its obligations fully until 2033. This information is paramount for current beneficiaries, future retirees, and policymakers alike, as it shapes discussions around the program’s long-term sustainability and potential reforms. Understanding the nuances of this report, including the factors influencing these projections and the implications for the future, is essential for every American concerned about their financial security. Let’s delve into the specifics of why the Social Security Administration Projects Solvency Until 2033 – Latest Actuarial Report Details.
Understanding the Latest Actuarial Report
The annual Social Security Trustees’ Report is a comprehensive document that provides a detailed assessment of the program’s financial state. It includes projections for the next 75 years, offering a long-term outlook on its ability to pay benefits. This report is not merely a forecast; it’s a critical tool for understanding the demographic and economic assumptions underpinning Social Security’s future.
Each year, actuaries and economists from the Social Security Administration (SSA) meticulously analyze various factors, from birth rates and mortality rates to economic growth and wage inflation. These complex calculations allow them to project the income and outgo of the Old-Age and Survivors Insurance (OASI) and Disability Insurance (DI) Trust Funds. The combined OASI and DI Trust Funds are the financial reservoirs from which Social Security benefits are paid.
Key Components of the Report
The actuarial report is structured to provide transparency and detail regarding the program’s financial standing. It breaks down the trust funds’ operations into several key areas, allowing for a thorough examination of their health.
Income Sources: Primarily from payroll taxes (FICA and SECA), which fund the majority of benefits.
Expenditures: Payments for retirement, survivor, and disability benefits, along with administrative costs.
Demographic Assumptions: Projections on birth rates, mortality rates, immigration, and life expectancy.
Economic Assumptions: Forecasts for wage growth, inflation, interest rates, and unemployment.
The report’s projection that the combined trust funds will be able to pay 100 percent of scheduled benefits until 2033 means that, under current law and assumptions, there’s a decade before the program would face a shortfall. After 2033, if no legislative action is taken, the funds would be able to pay approximately 80% of scheduled benefits, highlighting the need for future adjustments.
Factors Influencing the Solvency Projection
Several demographic and economic factors significantly influence the Social Security Administration’s solvency projections. These elements interact in complex ways, making accurate long-term forecasting a challenging but essential task. Understanding these drivers helps to contextualize the 2033 solvency date and the implications for future policy discussions.
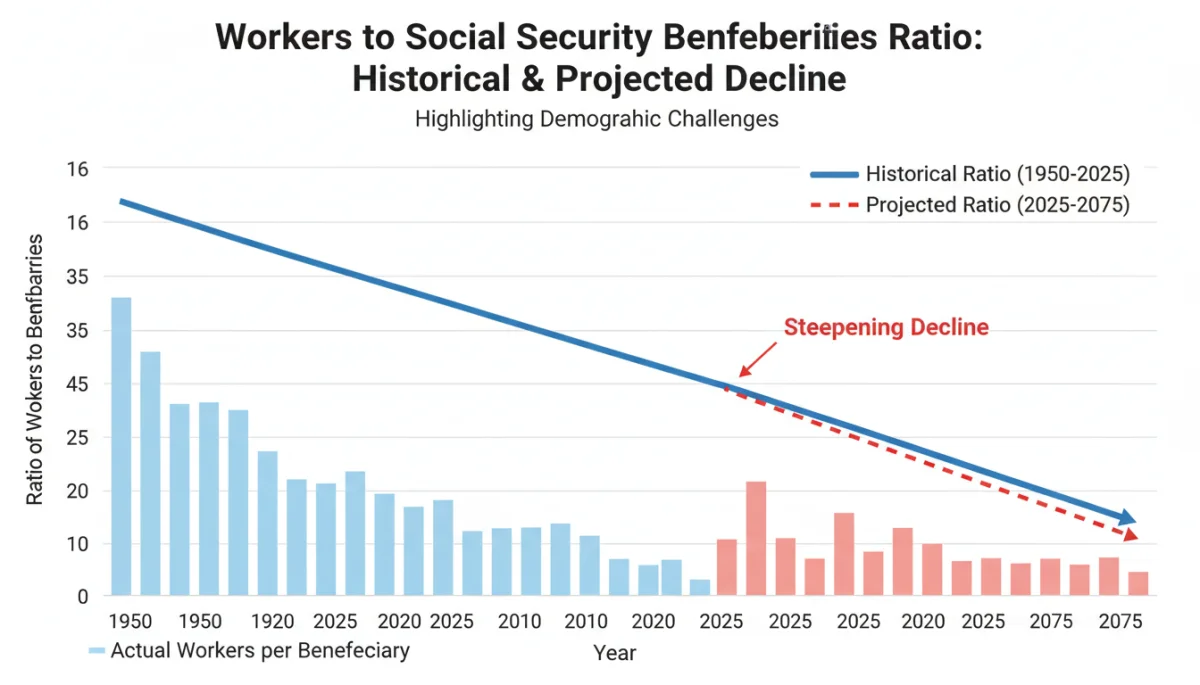
One of the primary demographic factors is the aging of the U.S. population. The baby boomer generation, a large cohort, is increasingly moving into retirement, leading to a higher number of beneficiaries relative to the number of workers contributing through payroll taxes. This shift in the worker-to-beneficiary ratio places greater strain on the system’s financial resources.
Demographic Shifts and Their Impact
The changing age structure of the population is a continuous challenge for pay-as-you-go systems like Social Security. Lower birth rates in recent decades mean fewer new workers are entering the workforce to support the growing number of retirees. Additionally, increased life expectancy means individuals are receiving benefits for longer periods.
Lower Birth Rates: Fewer new workers contributing to the system.
Increased Life Expectancy: Beneficiaries receive payments for more years.
Aging Population: A larger proportion of retirees compared to working-age individuals.
These demographic trends are not new, but their cumulative effect is becoming more pronounced, contributing to the projected depletion of the trust funds. The actuaries carefully model these trends to provide the most accurate possible outlook.
Economic Assumptions and Volatility
Beyond demographics, economic factors play an equally critical role in determining Social Security’s financial health. Wage growth, inflation, and interest rates directly impact the program’s income and investment returns. Economic volatility can introduce uncertainty into these projections, requiring regular updates and adjustments.
Wage growth is particularly important because Social Security’s primary funding comes from payroll taxes. Strong wage growth means more tax revenue flowing into the trust funds. Conversely, periods of slow wage growth or high unemployment can reduce the income stream, accelerating the depletion of reserves.
Key Economic Variables
The actuaries make assumptions about future economic conditions, which are inherently subject to change. These assumptions are a crucial part of the solvency projection.
Inflation: Affects the cost of living adjustments (COLAs) for benefits.
Interest Rates: Influences returns on invested trust fund reserves.
Unemployment Rates: Lower employment means fewer contributors.
The current economic climate, including post-pandemic recovery and inflationary pressures, adds layers of complexity to these forecasts. The Social Security Administration’s report takes these dynamic conditions into account, providing the most up-to-date assessment based on available data and expert analysis.
Implications of the 2033 Solvency Date
The projection that the Social Security trust funds will be able to pay 100 percent of scheduled benefits until 2033 carries significant implications for policymakers and the public. While a decade may seem like a distant future, the nature of Social Security reform means that discussions and decisions need to begin well in advance to ensure a smooth transition and maintain public confidence.
For current retirees and those nearing retirement, the 2033 date means that their scheduled benefits are secure for the foreseeable future. However, it also signals that legislative action will likely be necessary to ensure the program’s long-term viability beyond that point. This creates a sense of urgency for political leaders to address the issue proactively.
What Happens After 2033?
It’s crucial to clarify that Social Security does not cease to exist after 2033. Instead, the trust funds would be able to pay a significant portion of scheduled benefits, estimated to be around 80%. This means that benefits would be reduced across the board if no legislative changes are implemented. Such a reduction would have profound impacts on millions of Americans who rely on these benefits.
Benefit Reductions: Potential decrease in payments if no action is taken.
Policy Debates: Intensified discussions on reform options.
Public Confidence: Impact on trust in the program’s future.
The 2033 date serves as a powerful call to action, prompting stakeholders to explore various solutions to strengthen Social Security for future generations. These solutions typically involve a combination of revenue increases and benefit adjustments.
Potential Solutions and Policy Debates
Addressing the long-term solvency of Social Security is a complex challenge with no single easy answer. Various proposals have been put forth by economists, policymakers, and advocacy groups, each with its own set of advantages and disadvantages. The debate often centers on balancing the needs of current and future beneficiaries with the economic realities of funding the program.
One common category of solutions involves increasing revenue. This could be achieved through raising the payroll tax rate, increasing the amount of earnings subject to Social Security taxes (the taxable maximum), or diverting other government revenues to the trust funds. Each of these approaches would require legislative changes and would have different impacts on workers and employers.
Commonly Discussed Reform Options
The spectrum of potential reforms is broad, reflecting diverse perspectives on how best to ensure Social Security’s future. These options are often debated in political arenas.
Raising the Full Retirement Age: Gradually increasing the age at which individuals can claim full benefits.
Adjusting the Taxable Maximum: Applying Social Security taxes to a higher amount of earnings.
Modifying Cost-of-Living Adjustments (COLAs): Changing the formula used to calculate annual benefit increases.
Increasing Payroll Tax Rates: A direct increase in the percentage of earnings contributed.
Another set of solutions focuses on adjusting benefits. This might involve gradually raising the full retirement age, altering the formula for calculating initial benefits, or modifying the cost-of-living adjustments (COLAs). Any changes to benefits would need to be carefully designed to avoid undue hardship, especially for vulnerable populations. The political will to implement these changes will be critical in the coming years as the 2033 deadline approaches.
The Importance of Early Action
The Social Security Administration’s projection of solvency until 2033 underscores the critical need for early and decisive action. While a decade may seem like ample time, the nature of large-scale social programs and the political process means that reforms are best implemented gradually and with significant public input. Delaying action can lead to more drastic measures being required in the future, potentially creating greater economic disruption and uncertainty.
Early intervention allows for a phased approach to any necessary adjustments, whether they involve revenue increases or benefit modifications. This gradual implementation can minimize the impact on individuals and provide ample time for people to adjust their retirement planning accordingly. It also fosters greater public confidence in the program’s long-term stability.
Benefits of Proactive Reform
Taking action sooner rather than later offers several advantages, both for the program and for its beneficiaries.
Gradual Implementation: Allows for smaller, less disruptive changes over time.
Increased Public Confidence: Demonstrates commitment to the program’s future.
Reduced Uncertainty: Provides clarity for retirement planning.
Broader Consensus: More time for political negotiation and compromise.
The current report provides a valuable window of opportunity for policymakers to engage in constructive dialogue and develop sustainable solutions. Ignoring the projections or delaying action could lead to more difficult choices down the road, potentially impacting millions of Americans who rely on Social Security for their financial well-being.
Personal Planning in Light of the Report
For individual Americans, the Social Security Administration’s latest actuarial report serves as an important reminder to review and potentially adjust their personal retirement planning strategies. While the 2033 solvency projection offers a degree of near-term stability, the long-term outlook beyond that date suggests that relying solely on Social Security benefits may not be sufficient for a comfortable retirement.
It’s prudent for individuals, especially younger workers, to consider Social Security as one component of a broader retirement strategy. Diversifying retirement savings through 401(k)s, IRAs, and other investment vehicles can provide a stronger financial foundation, mitigating potential future changes to Social Security benefits. Understanding the report’s details can empower individuals to make informed decisions about their financial future.
Steps for Individual Financial Planning
Taking proactive steps now can significantly enhance your financial security in retirement, regardless of future Social Security reforms.
Review Your Retirement Goals: Reassess what you expect from retirement and how you plan to fund it.
Increase Personal Savings: Maximize contributions to 401(k)s, IRAs, and other investment accounts.
Consult a Financial Advisor: Get personalized advice on how to build a robust retirement plan.
Stay Informed: Keep abreast of legislative discussions and potential changes to Social Security.
Ultimately, the Social Security Administration’s report is a call for both collective action by policymakers and individual responsibility in financial planning. By understanding the challenges and opportunities presented by the latest projections, Americans can better prepare for a secure and stable retirement.
Key Aspect
Brief Description
Solvency Projection
Social Security trust funds projected to pay 100% of benefits until 2033.
Post-2033 Outlook
Approximately 80% of scheduled benefits payable if no legislative changes occur.
Key Factors
Aging population, lower birth rates, increased life expectancy, and economic variables.
Call to Action
Urgent need for policymakers to address long-term sustainability and for individuals to plan.
Frequently Asked Questions About Social Security Solvency
What does ‘solvency until 2033’ mean for Social Security?▼
It means that, under current law, the Social Security trust funds are projected to have sufficient reserves to pay 100% of all scheduled benefits until the year 2033. After this date, without legislative changes, the program would still be able to pay about 80% of promised benefits.
Will Social Security run out of money completely after 2033?▼
No, Social Security will not run out of money completely. Even if the trust funds are depleted, ongoing payroll tax contributions will continue to fund a significant portion of benefits. The program would still be able to pay approximately 80% of scheduled benefits.
What are the main reasons for the projected solvency date?▼
The primary reasons include demographic shifts like the aging baby boomer generation, lower birth rates, and increased life expectancy. Economic factors such as wage growth, inflation, and interest rates also play a significant role in the trust funds’ financial health.
What actions can be taken to extend Social Security’s solvency?▼
Potential actions include increasing the payroll tax rate, raising the taxable maximum earnings subject to Social Security taxes, adjusting the full retirement age, or modifying the cost-of-living adjustment formula. A combination of these approaches is often considered.
How should individuals plan for retirement given this report?▼
Individuals should view Social Security as one part of their retirement income. It’s advisable to maximize personal savings through 401(k)s and IRAs, diversify investments, and consider consulting a financial advisor to create a comprehensive and resilient retirement plan.
Conclusion
The latest actuarial report from the Social Security Administration, projecting solvency until 2033, provides a clear and urgent snapshot of the program’s financial future. While the system remains robust for the coming decade, the report underscores the necessity for proactive legislative action to ensure its long-term sustainability beyond that date. The interplay of demographic shifts and economic factors continues to challenge the program, demanding thoughtful and balanced solutions from policymakers. For individual Americans, this report is a crucial reminder to engage actively in personal retirement planning, considering Social Security as a foundational, yet not exclusive, component of their financial security. By addressing these challenges now, we can safeguard this indispensable program for generations to come, fostering confidence and stability for millions of beneficiaries.